
The Three Most Common Mortgage Types in the Netherlands Explained
When buying a home, you will need to choose a mortgage type. In the Netherlands, three main types are most common: the annuity mortgage, the linear mortgage, and the interest-only mortgage. Each type has its own way of repaying the loan and a different pattern of monthly payments. Below, we explain the differences and show how the costs work out in practice.
1. The Annuity Mortgage
With an annuity mortgage, you pay a fixed gross monthly amount (interest + principal repayment combined) throughout the entire term. This provides certainty about your monthly expenses, as long as the interest rate does not change.
-
At the beginning, this amount consists largely of interest and only a small portion of principal repayment.
-
As the debt decreases, the interest portion declines and the repayment portion grows.
-
The tax benefit from mortgage interest deduction is greatest in the early years but decreases as you pay less interest. As a result, your net monthly payments gradually increase over time.
Best suited for: households that value stability and predictability in their monthly expenses.
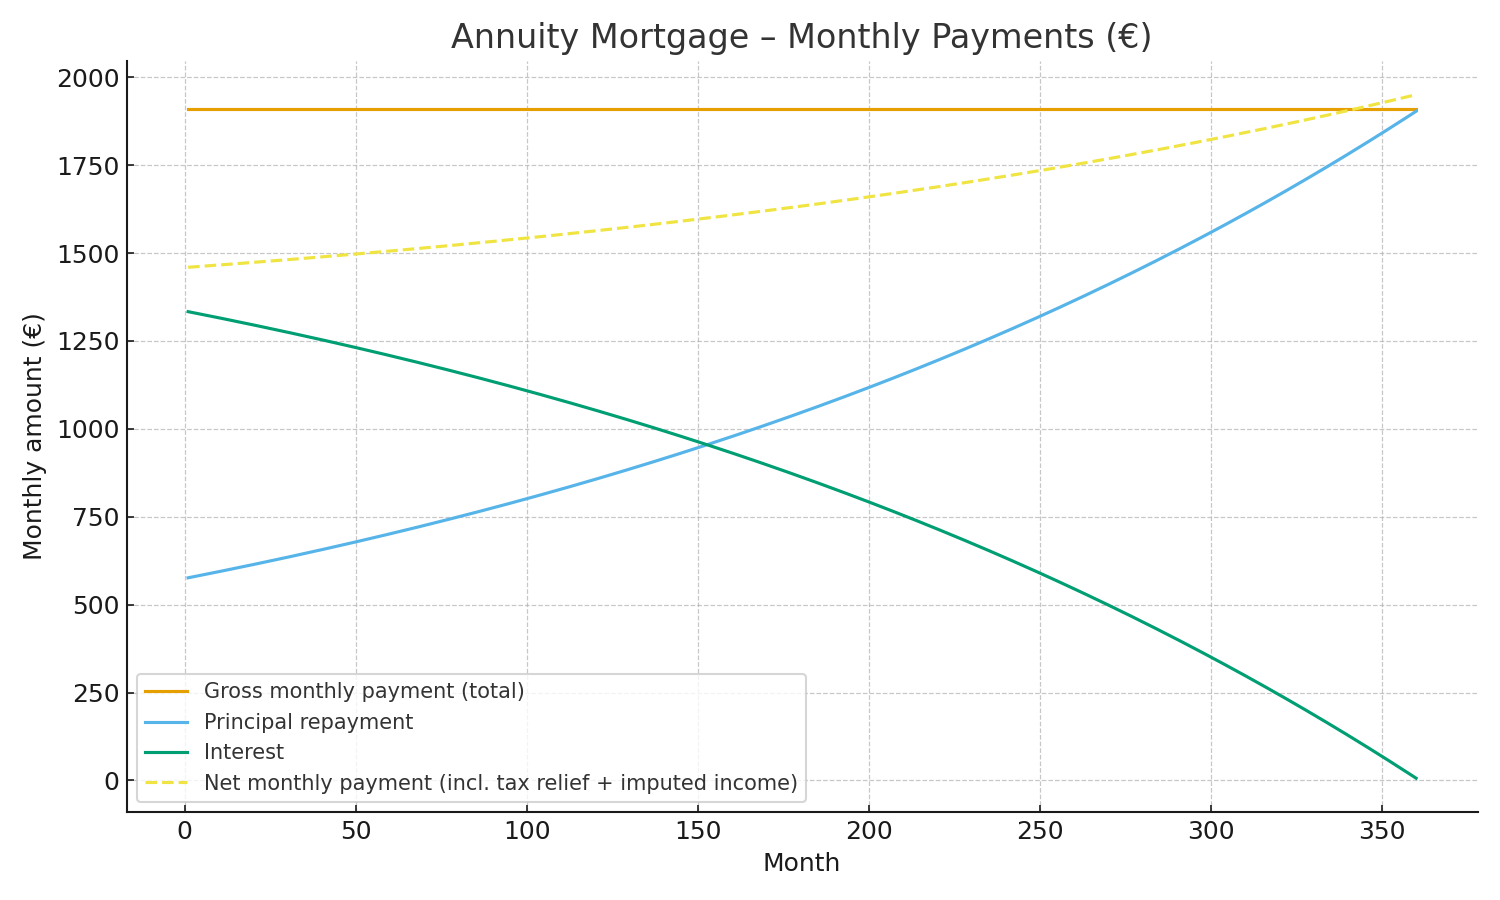
Mortgage €400.000 | Interest 4% | WOZ €350.000,-
Mortgage €400.000 | Interest 4% | WOZ €350.000,-
2. The Linear Mortgage
With a linear mortgage, you repay a fixed amount of principal each month. Interest is calculated on the remaining debt, which means your interest costs, and therefore your gross monthly payments, steadily decrease over time.
-
The initial monthly payments are higher compared to an annuity mortgage.
-
However, you repay your debt faster and the total interest paid over the full term is lower.
-
Because the interest portion declines quickly, your tax benefit also diminishes sooner. Your net monthly payments fall over time, but not as sharply as the gross payments.
Best suited for: people who can afford higher monthly costs at the start and want to build up home equity faster while keeping total costs lower.
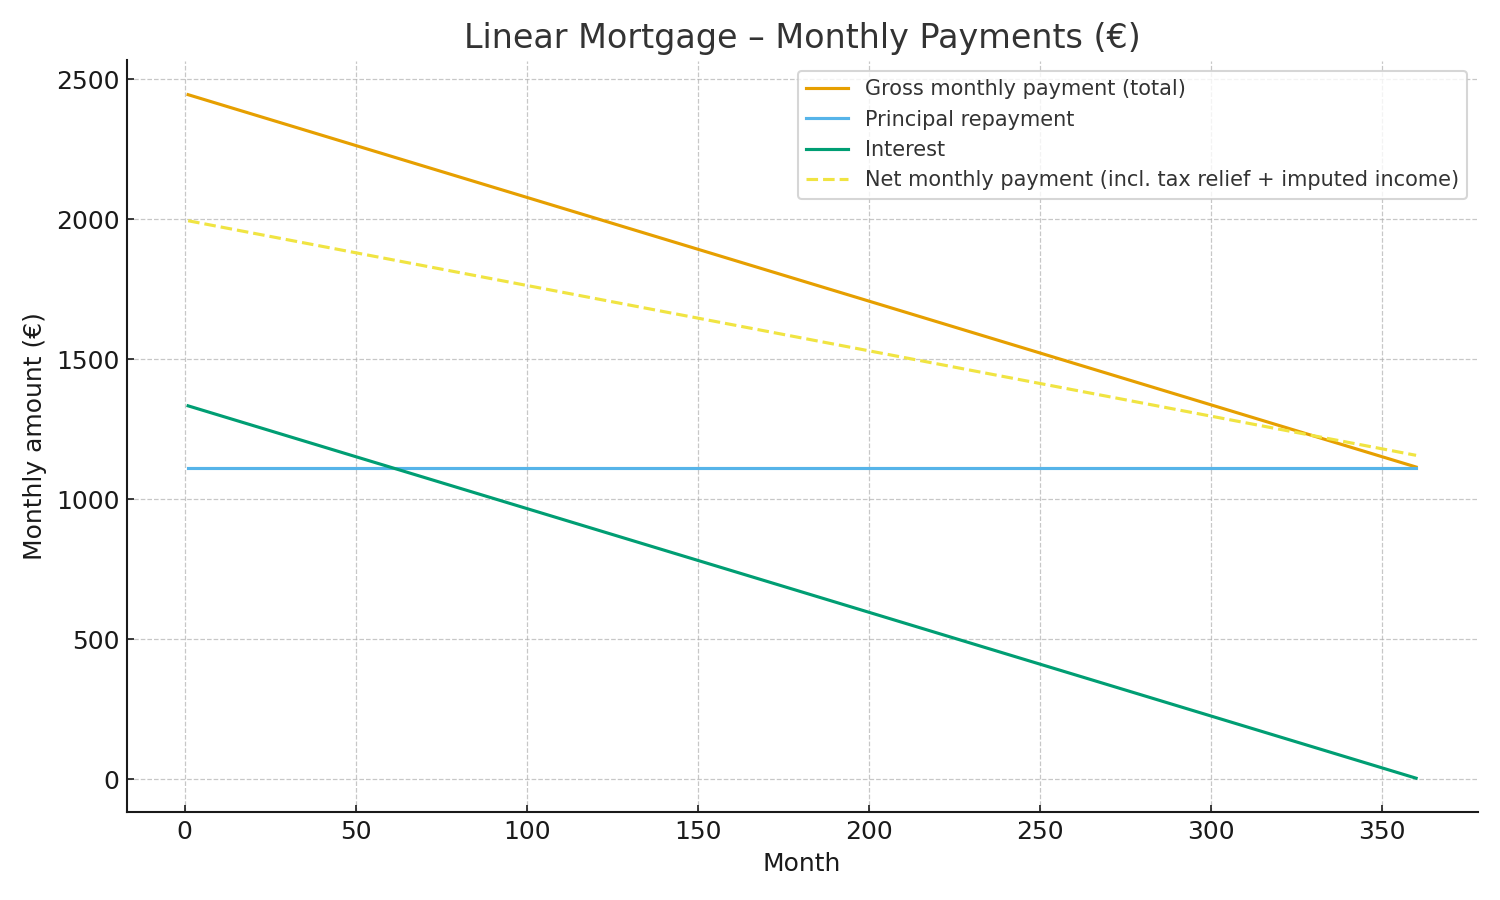
Mortgage €400.000 | Interest 4% | WOZ €350.000,-
3. The Interest-Only Mortgage
With an interest-only mortgage, you only pay interest and do not repay any principal during the term. At the end of the term, the full loan balance remains outstanding. You then need to refinance, repay using savings, or sell the property.
-
The monthly payments are low, since you only pay interest.
-
However, you do not build equity in your home through repayments.
-
For new mortgages, interest on an interest-only loan is no longer tax-deductible. This means the net monthly payments are often the same as the gross payments, except for the small extra cost of the imputed income (eigenwoningforfait).
Best suited for: people who want low monthly costs now and plan to settle the debt later (for example, with an inheritance, savings, or proceeds from selling the home). Nowadays, banks usually limit interest-only mortgages to a maximum of 50% of the property value.
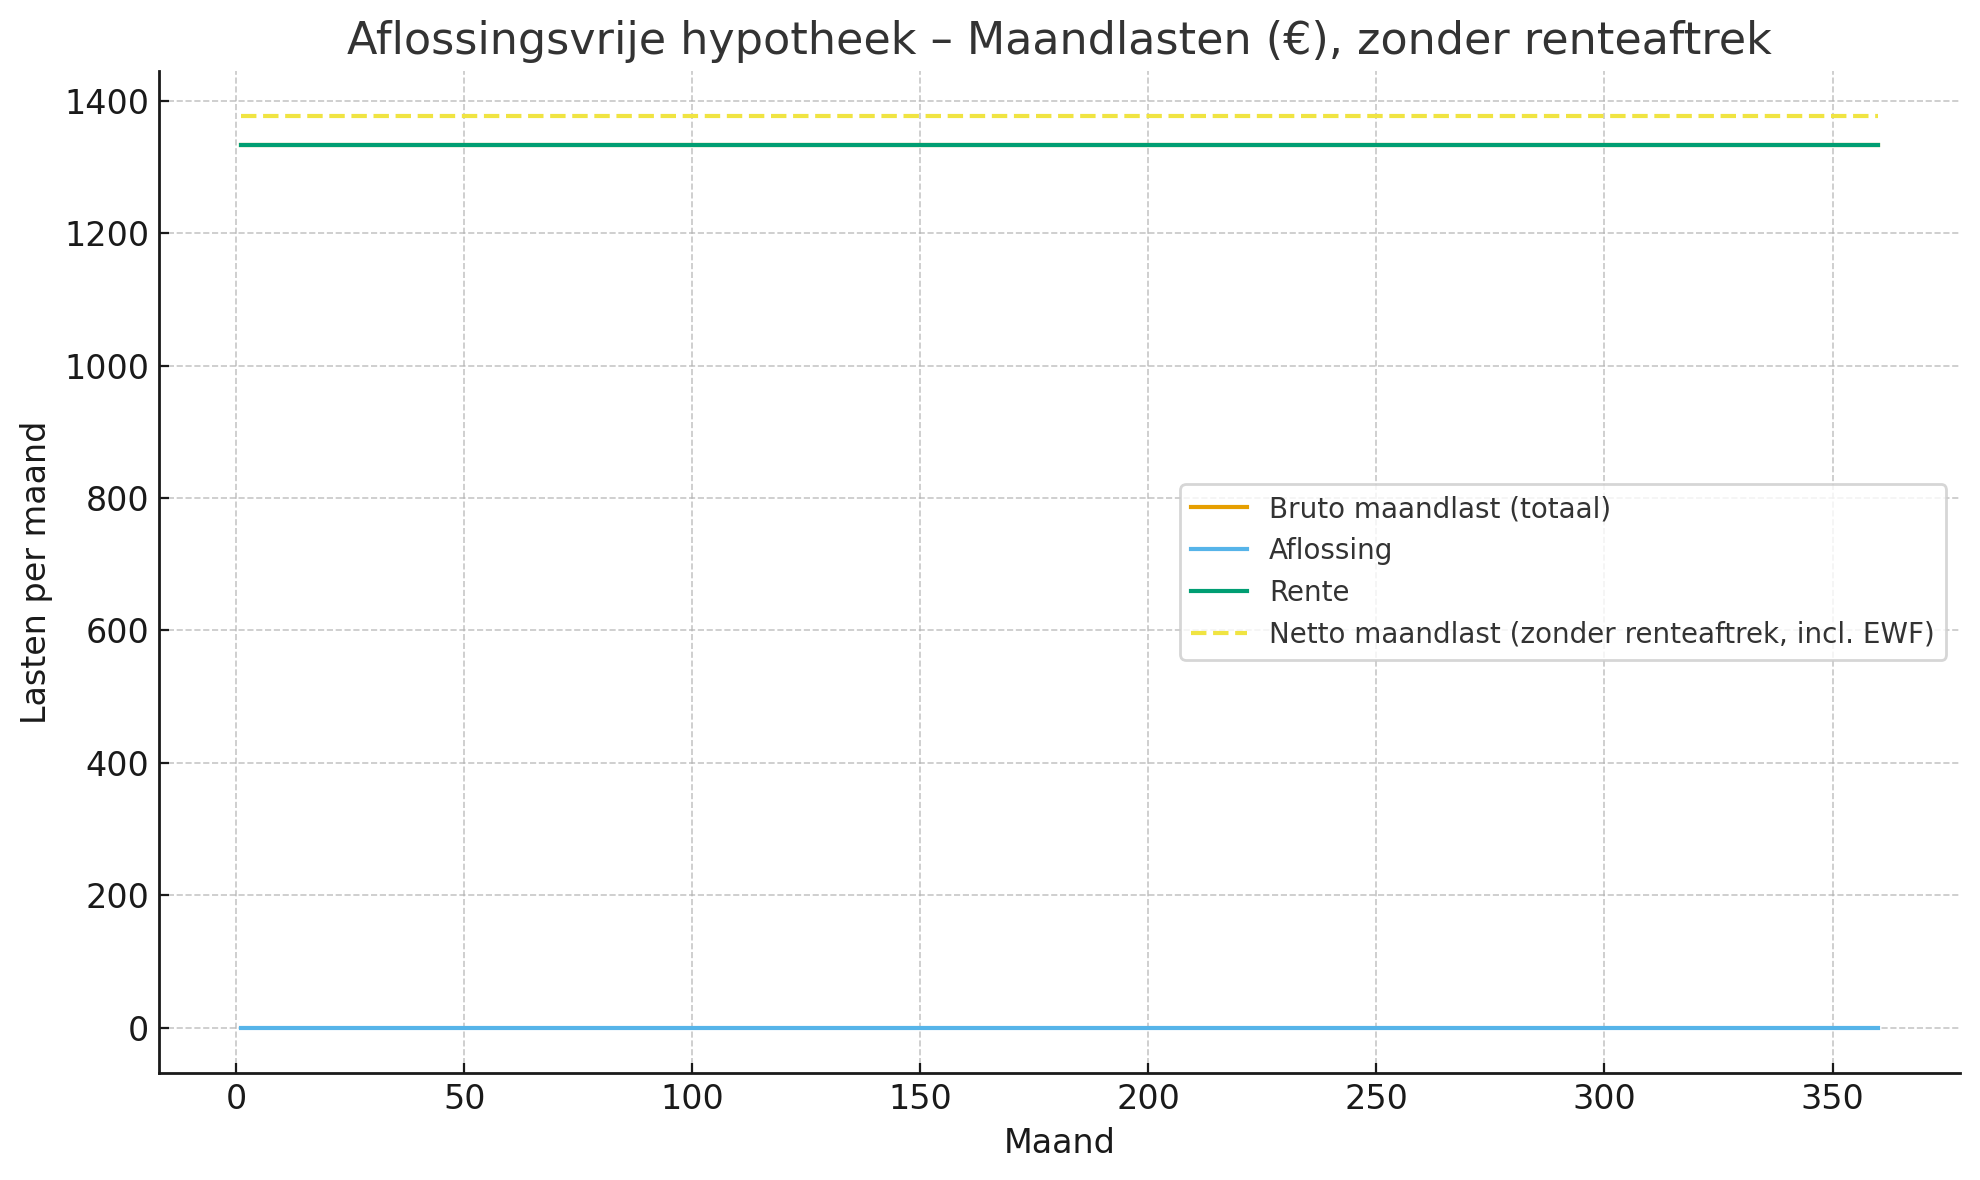
Mortgage €400.000 | Interest 4% | WOZ €350.000,-